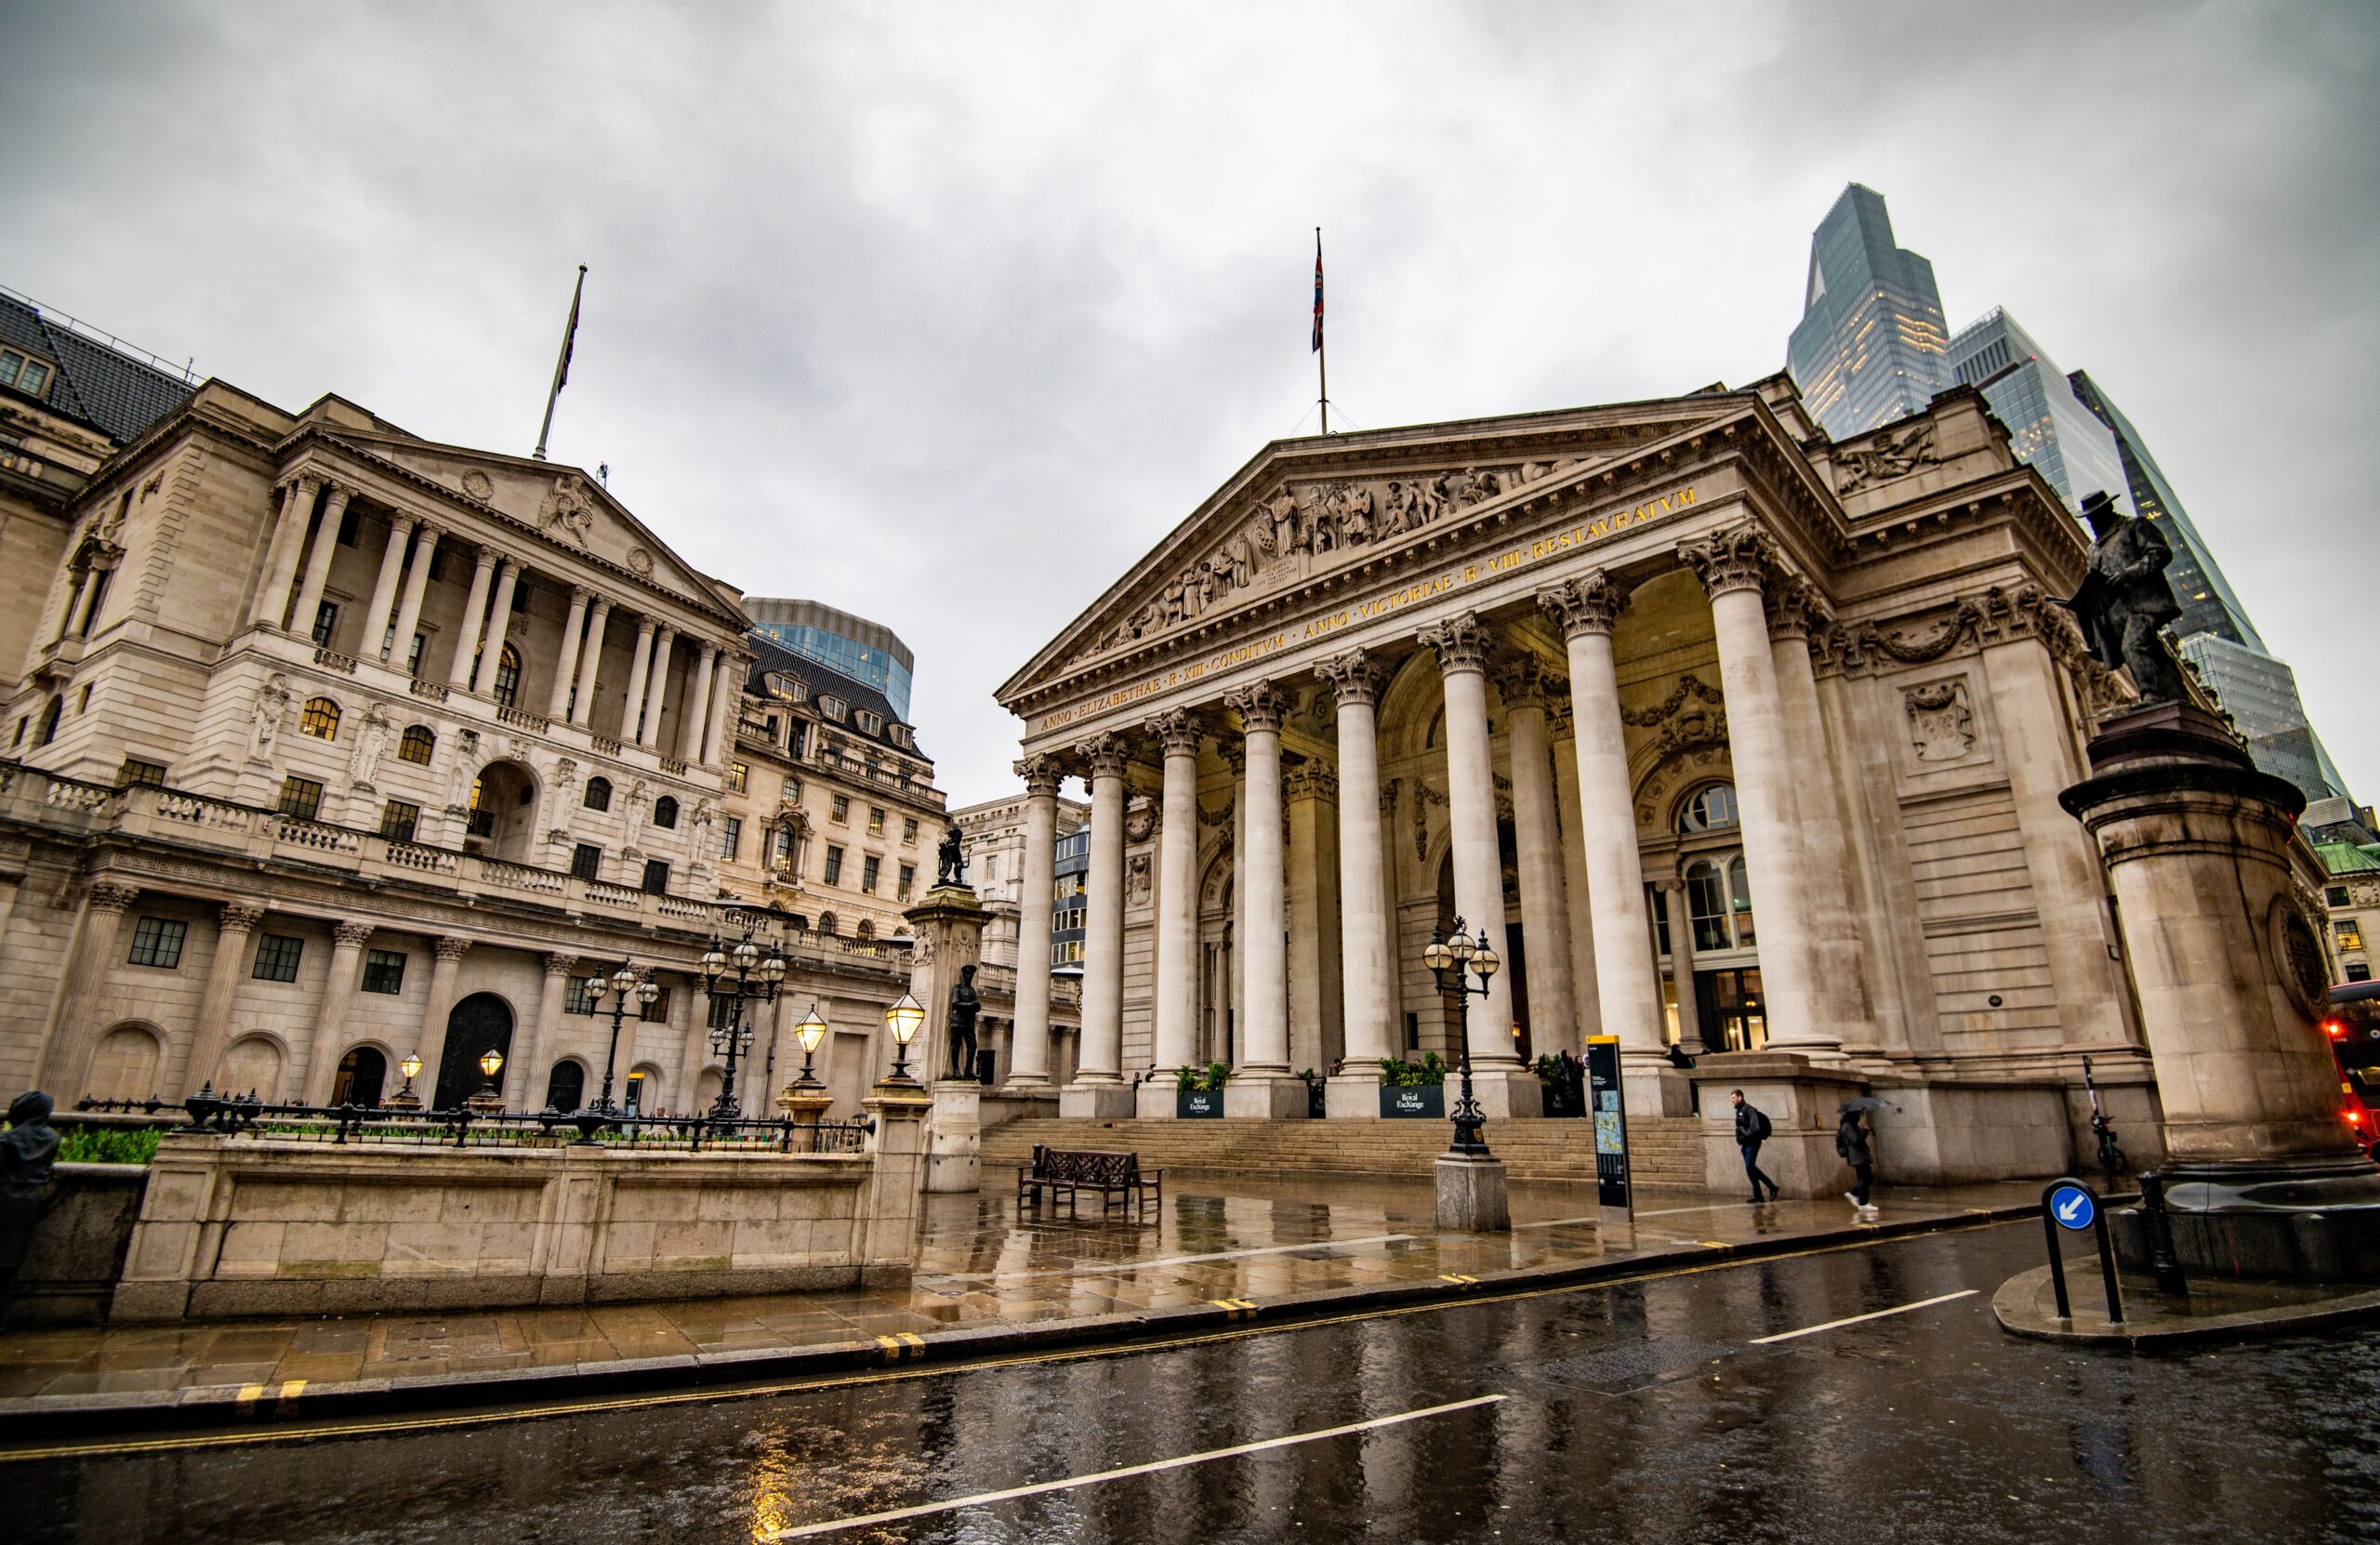
Former members of the Bank of England’s monetary policy committee (MPC) have called on governor Andrew Bailey to scale back or halt the central bank’s bond-selling programme, warning it is worsening the government’s record-high borrowing costs.
Britain’s long-term gilt yields have climbed to their highest level in nearly three decades, piling pressure on chancellor Rachel Reeves ahead of the autumn budget on 26 November. While global factors, including Donald Trump’s trade war and tensions over the US Federal Reserve, are driving markets, the Bank has acknowledged that its £100bn programme of quantitative tightening (QT) is adding to the strain.
Since last year, the Bank has sold around £100bn of gilts from its £895bn crisis-era portfolio, leaving holdings worth about £560bn. Investors expect QT to be trimmed to £70bn in the year ahead, though fewer bonds are due to mature, meaning active sales would remain high unless adjusted.
Michael Saunders, a former MPC member, said continuing at the current pace risked “undesirable” upward pressure on yields, while Sushil Wadhwani urged a halt to active sales, arguing for passive QT instead. Andrew Sentance, another ex-member, said scaling back to £70bn would be sensible but stressed the Bank’s priority was inflation control, not easing fiscal pressure.
The IPPR thinktank estimates that halting active sales could save the Treasury over £10bn annually, though the Bank faces costs because it pays more on commercial bank reserves than it earns on gilt holdings.
The Bank is expected to hold interest rates at 4% this week while potentially signalling a QT slowdown, as markets brace for jobs and inflation data in the run-up to Reeves’s budget.